
What is WIBA? Who needs it? What does it cover? How much compensation can employees receive? And why should every employer take it seriously?
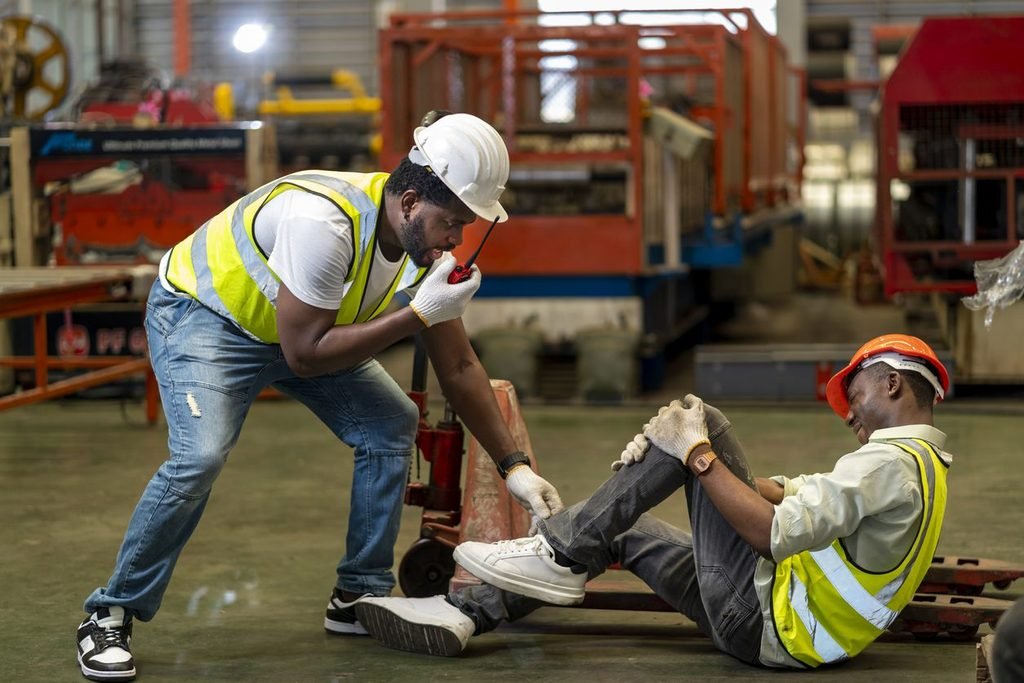
Imagine running a construction company. One of your employees falls from a height and sustains serious injuries. They require hospital treatment and are unable to work for several months. Who pays for their treatment? What happens to their income? And what financial responsibility does the employer carry?
These are some of the situations addressed by the Work Injury Benefits Act (WIBA), 2007.
Workplace accidents can happen in any industry. Whether you operate a construction company, a restaurant, a factory, a transport business or a small office, you have a responsibility to protect the people working for you.
In Kenya, WIBA provides a legal framework for compensating employees who suffer work-related injuries or occupational diseases. It also places specific obligations on employers, including the requirement to maintain appropriate insurance.
In this guide, we explain everything you need to know about WIBA insurance in Kenya, from its legal requirements and benefits to the types of employees covered and how your business can obtain a policy.
1. What is WIBA?
WIBA stands for the Work Injury Benefits Act, 2007. It is a Kenyan law that provides for compensation to employees who suffer injuries, disabilities or occupational diseases in the course of their employment.
The Act also provides for compensation to eligible dependants when an employee dies as a result of a work-related accident.
In simple terms, WIBA ensures that employees who suffer work-related injuries are entitled to compensation under the law, while providing employers with a framework for managing their financial liabilities. WIBA insurance is the insurance policy that employers obtain to cover liabilities arising under this Act.
It is important to understand that WIBA is not simply ordinary health insurance or a general employee benefit. It is a specific form of employer liability insurance connected to workplace injuries and occupational diseases.
2. Is WIBA insurance mandatory in Kenya?
Yes. WIBA insurance is a legal requirement for employers in Kenya.
Section 7 of the Work Injury Benefits Act requires every employer to obtain and maintain an insurance policy with an approved insurer to cover liabilities they may incur under the Act.
There is a statutory exemption for employers who obtain and maintain an approved security arrangement that satisfies the requirements of the Act.
This means employers cannot simply decide whether or not to protect themselves against work-related compensation liabilities.
Failure to comply with the insurance requirement is an offence. An employer convicted of contravening section 7 may face a fine of up to KSh100,000, imprisonment for up to three months, or both. Continued non-compliance after conviction can attract additional daily penalties.
The requirement applies to businesses across different industries and sizes. It is not reserved for large corporations or businesses operating in particularly dangerous environments. If you employ people, WIBA should be part of your business compliance arrangements.
3. Who is required to have WIBA insurance?
The Act applies broadly to employers in both the public and private sectors.
It covers employees working in different industries, including:
Construction and contracting businesses
Contractors, construction companies, engineers and building firms employ people who may face risks such as falls, equipment-related injuries and accidents involving construction materials.
Manufacturing and factories
Factory employees may operate machinery, handle chemicals and work in environments where workplace injuries can occur.
Transport and logistics businesses
Drivers, loaders, warehouse employees and logistics personnel may face occupational risks while performing their duties.
Security companies
Security guards and other security personnel may encounter physical risks while carrying out their assignments.
Cleaning and maintenance companies
Employees may handle cleaning chemicals, operate machinery or work in potentially hazardous environments.
Hotels and restaurants
Kitchen staff, cleaners, waiters, maintenance workers and other employees can suffer workplace accidents.
Offices and SMEs
Even employees working in relatively low-risk office environments can experience slips, falls, electrical accidents and other work-related injuries.
Does WIBA cover casual, temporary and part-time workers?
Yes, where they meet the Act’s definition of an employee.
The Act recognises employment relationships regardless of whether the agreement is written or verbal, or whether employees are paid by the day, week, month or according to work performed. It also expressly includes apprentices and indentured learners.
Importantly, a casual worker is not automatically excluded simply because they are paid daily. The Act excludes a person whose employment is casual and who is employed otherwise than for the purposes of the employer’s trade or business.
This distinction matters, particularly for contractors, farms, factories and businesses that regularly engage casual labour.
Domestic employees, including housekeepers, drivers and guards, can also fall within the Act’s definition of employees where the employment relationship meets the statutory requirements. The Act also applies to government employees, with an exception for members of the armed forces.
The important point: Do not assume that an employee is excluded from WIBA simply because they are temporary, casual, part-time or not employed on a permanent contract.
4. What does WIBA insurance cover?
WIBA insurance protects employers against covered compensation liabilities arising from qualifying workplace injuries and occupational diseases.
The main benefits include the following:
A. Accidental death
If an employee dies as a result of a work-related accident, their eligible dependants are entitled to compensation.
The statutory calculation of death compensation is governed by section 34 and the Third Schedule of the Act. The actual insurance benefit should be confirmed against the insurer’s policy schedule. The purpose is to provide financial support to eligible dependants who may have relied on the deceased employee’s income.
B. Permanent Total Disablement (PTD)
An employee may sustain an injury that permanently prevents them from returning to their occupation or earning an income in the same way as before.
The Act calculates compensation for permanent disablement on the basis of 96 months’ earnings.
For permanent total disablement, the assessment is based on the full applicable degree of disablement. For permanent partial disablement, compensation is adjusted according to the assessed percentage of disability.
For example, an employee who permanently loses the use of a limb may receive compensation based on the applicable assessment of their impairment.
C. Temporary Total Disablement (TTD)
Not every workplace injury results in permanent disability.
An employee may sustain an injury that temporarily prevents them from performing their normal duties.
For example, a construction worker may break a leg in an accident and require several months to recover.
Under section 28 of WIBA, an employee suffering temporary total disablement for three days or longer may qualify for periodic compensation equivalent to their earnings, subject to the statutory minimums and maximums.
These payments may continue for as long as the temporary disablement persists, but ordinarily cannot exceed 12 months.
Temporary partial disablement may also qualify for proportionate compensation.
The employee’s entitlement is subject to the provisions on full or partial salary payments and the other conditions under the Act.
D. Medical expenses
Workplace injuries can result in significant medical expenses.
WIBA provides for reasonable medical expenses arising from qualifying workplace accidents. These may include:
- Hospital and medical treatment.
- Surgical and dental treatment.
- Nursing services.
- Medicines and surgical dressings.
- Medical travel and related subsistence expenses.
- Artificial limbs, crutches and other necessary medical appliances.
What is the medical expenses limit?
Many standard WIBA insurance products advertise a medical expenses limit of approximately KSh100,000 per employee.
However, this is an insurance product limit commonly offered by insurers, not a universal maximum prescribed by the Act.
The actual amount available depends on the insurer’s policy terms and schedule. Businesses should confirm the medical expenses limit before purchasing cover.
E. Funeral expenses
Where an employee dies as a result of a work-related accident, reasonable funeral expenses are payable in addition to the applicable death compensation.
F. Occupational diseases
Not all workplace injuries happen suddenly.
Some employees develop illnesses after prolonged exposure to hazardous workplace conditions. Examples include:
- Respiratory diseases resulting from exposure to harmful dust.
- Occupational skin conditions caused by chemicals.
- Illnesses associated with exposure to toxic substances.
- Other qualifying occupational diseases arising from employment.
Section 38 of WIBA provides for compensation for both scheduled and other occupational diseases that arise out of and in the course of employment.
The relevant medical evidence and statutory requirements determine whether a particular condition qualifies.
5. What is WIBA Plus?
WIBA Plus is an extended insurance arrangement that combines WIBA with Group Personal Accident (GPA) benefits.
While WIBA addresses qualifying employment-related injuries and diseases, the GPA component can extend protection to accidental injuries and death outside working hours.
Depending on the policy, this can provide 24-hour protection, including weekends and off-duty periods.
For employers who want broader protection for their employees, WIBA Plus may be worth considering.
Always check the policy schedule to understand exactly what is covered, including geographical limits, exclusions and benefit limits.
6. Who pays for WIBA insurance?
The responsibility to obtain and maintain WIBA insurance rests with the employer.
Section 7 places this obligation on the employer, who must arrange the required policy with an approved insurer.
Employers should therefore budget for WIBA insurance as part of their business operating and compliance expenses.
Employees should not be expected to arrange the employer’s statutory insurance obligation themselves.
It is also important to distinguish the insurance premium from medical expenses. Section 50 of the Act expressly prohibits employers from demanding, receiving or deducting employee contributions towards the cost of medical aid provided under the Act.
Protecting employees against workplace injuries is an employer responsibility, not an optional expense to be passed on to workers.
7. WIBA vs Group Personal Accident (GPA): What is the difference?
WIBA and GPA are often confused because both can provide financial benefits following accidental injury or death.
However, they serve different purposes.
| WIBA | GPA |
|---|---|
| A statutory insurance requirement for employers, subject to the Act’s exemption. | Generally an optional employee insurance benefit. |
| Covers qualifying work-related injuries and occupational diseases. | Covers accidental injuries and death according to the policy. |
| Compensation follows the WIBA statutory framework. | Benefits are determined by the GPA policy and selected limits. |
| Primarily relates to the course and scope of employment. | Can extend to accidents outside working hours. |
| Protects against employer liabilities under WIBA. | Provides additional personal accident protection. |
An employer can purchase both through a combined WIBA Plus arrangement.
The key takeaway is that GPA does not replace the employer’s WIBA obligation.
8. Why is WIBA insurance important to your business?
WIBA is more than a compliance requirement. It is an important part of responsible business management.
Here are some reasons every employer should take it seriously.
It protects your business financially
A serious workplace accident can result in substantial compensation liabilities, medical expenses and other financial obligations.
Having appropriate insurance helps protect the business against covered liabilities, subject to the policy terms.
It protects your employees
Employees are central to the success of any business.
WIBA provides a framework through which workers who suffer qualifying workplace injuries or occupational diseases can receive compensation.
It protects employees’ families
An employee’s death can have serious financial consequences for their dependants.
The Act provides for compensation to eligible dependants, helping support those who relied on the employee financially.
It helps your business meet legal obligations
Maintaining the required insurance is part of complying with Kenyan employment and workplace injury legislation.
Failure to do so can expose the employer to penalties and financial liabilities.
It demonstrates responsible business practices
Businesses that take employee welfare seriously demonstrate a commitment to responsible employment practices.
Appropriate workplace insurance is one part of that commitment.
It supports business continuity
Workplace accidents can disrupt operations and create unexpected financial pressure.
Insurance helps businesses manage covered financial consequences and concentrate on maintaining their operations.
9. How much does WIBA insurance cost in Kenya?
There is no single premium that applies to every business.
The cost depends on several factors, including:
- Number of employees.
- Total annual employee earnings.
- Nature of the business.
- Type of work performed.
- Occupational risks associated with the work.
- Insurance benefits and policy limits selected.
For example, a construction company with employees working at heights and operating heavy machinery may have a different insurance risk profile from an office-based consultancy.
10. Get your WIBA insurance through Zabuni Ltd
At Zabuni Ltd, we understand that businesses need straightforward insurance arrangements without unnecessary delays.
We help employers obtain WIBA cover so they can meet their insurance requirements and protect their businesses against covered workplace injury liabilities.
Why choose Zabuni for your WIBA cover?
1. One-hour turnaround time
We offer a one-hour processing turnaround, subject to receiving the required information and completing the necessary underwriting and payment arrangements.
2. No maximum limit
Our WIBA cover offering has no stated maximum limit under the arrangement we provide.
3. Support for different businesses
Whether you run a construction company, a manufacturing business, a logistics firm or an SME, we can help you arrange appropriate WIBA cover.
You do not need to wait until an employee gets injured to start thinking about workplace protection.
Get your business covered and take employee protection seriously.
Ready to obtain your WIBA cover? Get in touch with Zabuni Ltd today.
- Call / WhatsApp Us:
- Sales 1: +254 748 997 987
- Sales 2: +254 716 462 675
- Email: customercare@zabuniltd.com
- Office Address: Utumishi Co-Op House, Mamlaka Road, Nairobi, Kenya.
Frequently Asked Questions (FAQs) About WIBA in Kenya
1. Is WIBA insurance compulsory in Kenya?
Yes. Section 7 of the Work Injury Benefits Act, 2007 requires employers to obtain and maintain insurance covering their liabilities under the Act, subject to the statutory exemption for approved security arrangements.
2. Does WIBA cover casual workers?
Yes, where they qualify as employees under the Act. Being paid daily or working temporarily does not automatically exclude someone from WIBA protection.
3. Does WIBA cover domestic workers?
Yes. Domestic workers such as housekeepers, guards and drivers can qualify as employees under the Act.
4. Does WIBA cover employees outside working hours?
Standard WIBA generally covers qualifying employment-related injuries and occupational diseases. Employers seeking broader 24-hour accidental injury protection can consider WIBA Plus, which combines WIBA with GPA benefits.
5. What is the maximum WIBA compensation?
The applicable compensation depends on the type and degree of disablement, employee earnings and statutory requirements. Permanent disablement is calculated using a 96-month earnings basis, adjusted according to the degree of disablement. Other benefits follow their respective statutory provisions and applicable insurance terms.
6. Can a small business obtain WIBA insurance?
Yes. WIBA is not restricted to large companies. Small businesses employing qualifying employees should also arrange the required cover.
7. Is WIBA the same as medical insurance?
No. Medical insurance generally provides healthcare benefits according to a medical policy. WIBA addresses compensation and medical aid arising from qualifying workplace injuries and occupational diseases.
8. Is WIBA the same as GPA?
No. WIBA is a statutory employer insurance requirement, while GPA is generally an additional personal accident benefit. A combined WIBA Plus policy can provide both types of protection.
9. How long does it take to obtain WIBA insurance through Zabuni?
Zabuni offers a one-hour turnaround, subject to receiving complete information and completing the insurer’s underwriting and payment requirements.
10. Can a company have WIBA insurance without a maximum limit?
The scope and limits depend on the insurance arrangement and insurer’s written terms. Contact Zabuni to discuss the available no-maximum-limit offering and the specific cover required by your business.
Protect your employees. Protect your business. Stay compliant.
Get your WIBA cover through Zabuni Ltd.
 Insights · 18 min read
 Zabuni Ltd Services · 18 min read
 Insights · 2 min read